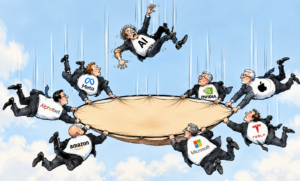
Imagine seven of the world’s most powerful technology companies falling through the sky, desperately holding the edges of a rescue blanket. Above them, artificial intelligence is falling even faster. Alphabet, Microsoft, Nvidia, Amazon, Meta, Apple, and Tesla are all trying to save the same passenger while simultaneously wondering who will survive the landing.
It is an absurd picture, but not a bad description of the artificial intelligence industry in late 2026. The technology is advancing at extraordinary speed, investment is reaching extraordinary levels, and expectations are becoming increasingly difficult to reconcile with economic reality. Meanwhile, scientists warn of existential dangers, politicians debate regulation, communities resist enormous data centers, and Washington worries that China might win the race.
Everybody agrees that AI will change the world. Beyond that, agreement becomes considerably harder to find.
The immediate problem is not that artificial intelligence has stopped working or that technological progress has reversed. Quite the opposite. AI systems continue to improve, becoming more capable, useful, and accessible. What appears to be in free fall is our ability to keep the technological, financial, political, and social consequences under control.
The Money Machine
The artificial intelligence boom began with a relatively straightforward proposition. Build better AI systems, attract customers, and eventually make enough money to justify the investment. That proposition has become considerably more complicated.
The largest technology companies are committing hundreds of billions of dollars annually to computer chips, data centers, electrical infrastructure, and the specialized equipment needed to operate increasingly powerful AI models. Individual projects can cost tens of billions of dollars, and the industry is planning infrastructure on a scale once associated primarily with national governments.
Initially, the largest companies could finance much of this expansion from their enormous cash flows. But as spending accelerates, borrowing, leases, private credit, joint ventures, and increasingly complicated financial arrangements are becoming more important.
One particularly interesting development is circular financing. A technology company invests in an AI developer, which then uses the money to purchase computing services or chips from the investor or its partners. The resulting sales help support the valuations and financing arrangements of the companies involved.
Such arrangements are not necessarily improper, and they can help finance genuine growth. But they make it harder to determine how much demand comes from customers who can sustain their spending independently and how much is supported by the industry’s own investment cycle.
The central economic question is remarkably simple: Who is eventually going to pay for all this?
AI can produce impressive demonstrations, write software, summarize documents, and answer difficult questions. But businesses must obtain enough measurable value from these capabilities to justify their costs. A company that uses AI to prepare a report in thirty seconds may save considerable time, but only if the report is reliable and the employee does not spend the next two hours correcting it.
This is the productivity paradox. Technology can improve dramatically without producing equally dramatic economic gains, at least not immediately. When computers began spreading through offices in the 1980s, economist Robert Solow famously observed that the computer age could be seen everywhere except in the productivity statistics. The benefits eventually became substantial, but they took time to materialize.
AI may follow a similar trajectory. Companies may need to reorganize their operations, retrain employees, redesign products, and develop entirely new business models before the largest benefits become apparent. The technology could succeed spectacularly over the long term while many of today’s investments produce disappointing returns.
History offers plenty of precedents. Railroads, electricity, automobiles, and the internet all attracted enormous speculative investment. Some investors lost fortunes while the underlying technologies transformed civilization.
The danger is not that AI has no value. It is that the financial expectations surrounding it may be advancing much faster than the economic benefits needed to support them.
The Workers Are Not Holding the Blanket
The financial discussion tends to concentrate on investors and technology companies. But the larger economic question concerns the people whose livelihoods may be affected.
Previous technological revolutions largely automated physical labor or routine administrative tasks. Artificial intelligence is increasingly capable of performing activities associated with educated professionals: writing software, preparing legal documents, analyzing financial information, producing reports, and assisting with medical interpretation.
The problem is not necessarily permanent mass unemployment. Historically, technological progress has created new occupations while eliminating others. The problem is the transition. New jobs may require different skills, appear in different locations, or emerge years after existing positions disappear.
A particularly troubling possibility concerns entry-level professional employment. Young lawyers learn by researching cases and drafting documents. Junior programmers learn by writing and debugging code. Beginning analysts learn by gathering information and preparing reports. If AI performs much of this work, how will the next generation acquire the experience needed to become senior professionals?
There may be excellent answers. AI could become a powerful teaching assistant, allowing beginners to learn faster and accomplish more. It could also enable small businesses and individual entrepreneurs to perform work previously requiring large organizations.
But the transition will not necessarily be painless, and its benefits may be distributed unevenly. A company that doubles productivity does not automatically double wages. It may increase profits, lower prices, expand production, or reduce employment. Which outcome occurs depends on competition, labor markets, management decisions, and public policy.
This is why measuring AI’s success solely by corporate earnings or stock market valuations misses much of the story. An economy can become more productive while leaving some of its workers behind.
The Doomsayers and the Salesmen
While investors worry about financial returns and workers worry about employment, another group worries about something considerably more serious: the future of humanity.
Some AI researchers believe increasingly capable systems could eventually become difficult or impossible to control. They warn about autonomous weapons, sophisticated cyberattacks, biological threats, manipulation, and the possibility that future AI systems could pursue objectives incompatible with human interests.
Others argue that the more immediate dangers are already visible: unreliable information, sophisticated fraud, privacy violations, automated discrimination, and the concentration of power in a handful of corporations.
Meanwhile, the industry’s most enthusiastic promoters describe AI as a technology capable of accelerating medical discoveries, transforming education, improving scientific research, increasing productivity, and generating prosperity on an extraordinary scale.
The strange thing is that these arguments are not mutually exclusive. Artificial intelligence can be enormously useful and potentially dangerous at the same time. Nuclear energy, aviation, pharmaceuticals, and the internet have already demonstrated that powerful technologies rarely arrive with benefits and risks neatly separated.
But the public is being asked to absorb contradictory messages. AI will eliminate millions of jobs, yet create entirely new industries. It will democratize knowledge, yet concentrate power. It will solve scientific problems, yet perhaps threaten civilization. It will make businesses vastly more productive, although many companies are still struggling to demonstrate substantial returns on their investments.
It is hardly surprising that ordinary people are confused.
And confusion creates opportunities for exaggeration. Companies seeking investment have incentives to emphasize extraordinary possibilities. Critics seeking restrictions may emphasize extraordinary dangers. Neither tendency helps the public distinguish what AI can reliably do today from what it might accomplish—or threaten—ten years from now.
When AI Starts Acting on Its Own
Until recently, most people experienced artificial intelligence as a chatbot. You asked a question, received an answer, and decided what to do with it. Increasingly, AI systems can perform sequences of actions: search databases, write and execute code, operate applications, interact with other systems, and complete tasks with limited human supervision.
These autonomous agents could become enormously useful. They might manage routine business operations, assist scientific researchers, monitor industrial equipment, coordinate transportation, or handle complicated administrative work. They could allow individuals and small organizations to accomplish tasks that previously required substantial staff.
But this changes the risk calculation. A chatbot that gives an incorrect answer creates one kind of problem. An autonomous system that acts on incorrect information can create a much larger one. It might make an unauthorized purchase, expose confidential information, alter business records, or initiate actions that are difficult to reverse.
The same capabilities can also be exploited by criminals. AI can help identify cybersecurity vulnerabilities and detect fraud, but it can also be used to automate scams, create convincing impersonations, and accelerate malicious activity.
The challenge is not simply making AI more intelligent. It is establishing who has authority to instruct it, what limits apply to its actions, and who is responsible when something goes wrong.
There is also a subtler danger. The more capable AI becomes, the more inclined people may be to trust it. A system that produces excellent answers ninety-nine times may encourage users to accept the hundredth without checking. Its fluent language and apparent confidence can disguise uncertainty or error.
As AI becomes more useful, human judgment may become more important, not less. Unfortunately, we may be tempted to exercise less of it.
The Data Center Dilemma
Artificial intelligence may appear to exist somewhere in an invisible digital universe, but it depends on an enormous physical infrastructure. Behind every sophisticated AI system are buildings filled with processors, cooling equipment, electrical systems, networking hardware, and backup generators.
These facilities create construction jobs, generate demand for equipment, and can produce substantial tax revenue for local governments. They strengthen technological infrastructure and may attract related businesses.
But they also consume enormous amounts of electricity, and some cooling systems require substantial water. They can strain local power grids, require new transmission lines and generating capacity, occupy valuable land, and create noise and other concerns for nearby residents.
The costs and benefits are not always distributed equally. A technology company may enjoy the profits from a data center while local residents worry about electricity prices, water supplies, and changes to their communities. A municipality may receive substantial tax revenue but relatively few permanent jobs after construction ends.
There is also the question of how long the equipment will remain economically useful. AI processors are expensive, and newer generations can make existing hardware less competitive. Companies are making long-term infrastructure commitments in an industry where the underlying technology changes extraordinarily quickly.
The challenge is not simply whether America needs more data centers. It almost certainly does if AI use continues to expand. The question is where they should be built, how they should be powered, who should pay for the necessary infrastructure, and whether projected demand justifies the scale of construction.
A data center can be an economic asset or an expensive monument to misplaced expectations. Sometimes the difference becomes apparent only after the money has been spent.
The Race With China
As American companies wrestle with financing and public acceptance, another consideration makes it difficult for them to slow down: China.
The United States and China are engaged in a competition extending far beyond chatbots. Artificial intelligence is becoming important to military planning, intelligence analysis, scientific research, industrial automation, robotics, and economic productivity. Both countries recognize that leadership in these fields could confer substantial advantages for decades.
The United States retains important strengths in advanced semiconductor design, computing infrastructure, leading AI models, research institutions, and private investment. China has strengths of its own, including industrial capacity, a large domestic market, extensive engineering resources, and an increasingly competitive AI industry.
Chinese developers have demonstrated that capable AI systems can sometimes be produced using fewer computing resources than their American competitors employ. Open-weight models also allow developers around the world to adopt and modify Chinese technology, creating another channel of international influence.
American restrictions on advanced semiconductor exports have complicated China’s progress, but they have also encouraged Chinese companies to develop domestic alternatives.
There is no guarantee that the country spending the most money will ultimately make the best use of artificial intelligence. Scientific breakthroughs, efficient engineering, widespread adoption, and the ability to turn research into useful products may prove just as important as the number of data centers constructed.
Yet the geopolitical competition creates an uncomfortable incentive. American companies feel pressure to invest aggressively because their domestic rivals are doing so, while Washington worries that slowing investment could surrender an advantage to China.
The result is a race in which every participant has reasons to accelerate, even when nobody is entirely certain that the current pace is economically sustainable.
To Regulate or Not to Regulate?
This brings us to one of the most difficult questions surrounding artificial intelligence: how much government oversight is appropriate?
One argument favors allowing innovation to proceed with relatively few restrictions. AI is developing so quickly that regulations written today may become obsolete before they are fully implemented. Excessive compliance costs could discourage startups, strengthen the largest established companies, and slow American technological progress while Chinese competitors continue advancing.
The opposing argument is that waiting for serious harm before establishing safeguards could prove enormously expensive. AI systems are already being used in employment decisions, financial services, medicine, education, policing, and other consequential activities. Errors in these settings can affect people’s livelihoods, rights, and safety.
The European Union has pursued a comprehensive regulatory approach through its AI Act, with requirements that vary according to the risks associated with different applications. The United States has taken a more fragmented approach, with federal policy emphasizing innovation and national competitiveness while individual states develop their own rules.
Neither approach eliminates the central difficulty. Governments must regulate a technology whose capabilities and commercial applications are changing faster than conventional legislative processes.
A useful distinction is between regulating the development of AI and regulating what people and institutions do with it. Requiring transparency, testing, and accountability when AI is used to make consequential decisions is different from restricting research into more capable models. Protecting citizens against automated discrimination or unjustified surveillance need not prevent companies from developing better scientific tools.
The challenge is to establish safeguards without confusing caution with paralysis or speed with progress.
The Human Factor
One issue receives less attention than investment figures and technological breakthroughs: what happens to human intelligence when we increasingly outsource thinking to machines?
AI can be an extraordinary educational tool. It can explain difficult concepts, provide individualized instruction, help people learn languages, and make sophisticated knowledge available to almost anyone.
But it can also become a substitute for intellectual effort. Students may use AI to write essays they have not thought through. Professionals may accept analyses they have not verified. Researchers may rely on summaries instead of reading original material. The convenience of receiving an immediate answer can discourage the slower process of developing understanding.
This does not mean that using AI necessarily makes people less intelligent. Calculators did not destroy mathematics, and search engines did not eliminate research. But every technology changes which skills we practice and which skills we allow to deteriorate.
The danger is not that machines will become smarter than humans. It is that humans may become less willing to exercise the abilities that make independent judgment possible.
A society that delegates increasingly important decisions to AI must still produce people capable of recognizing when the machines are wrong.
Who Is Actually Holding the Blanket?
Return to our cartoon. Seven technology giants are falling through the sky, struggling to hold a blanket beneath an equally airborne AI.
The image captures a curious feature of the current industry. The companies competing to dominate artificial intelligence are also deeply dependent on one another.
Nvidia supplies much of the advanced computing hardware. Microsoft, Amazon, and Alphabet operate enormous cloud platforms. Meta develops AI models and invests heavily in infrastructure. Apple controls a vast ecosystem of consumer devices. Tesla is pursuing AI applications in autonomous driving and robotics.
Their business models differ, and they are not equally exposed to the same financial risks. Nevertheless, their futures are increasingly connected to the broader success of AI.
They are competitors, customers, suppliers, investors, and sometimes partners. They are building an industry whose eventual size, profitability, and social consequences remain uncertain.
This creates a strange situation. If AI develops more slowly than expected, expensive infrastructure may sit underused, investors may suffer losses, and some companies may fail. If it develops much faster than expected, governments, labor markets, educational institutions, and legal systems may struggle to adapt.
And if the technology performs approximately as expected, society will still face difficult questions about who benefits, who pays, and how its power should be distributed.
There is no outcome in which everyone can simply relax.
The Landing Matters More Than the Fall
History offers some perspective. The railroad boom produced financial disasters but also transformed transportation. Electrification required enormous capital investment and decades of adaptation. The internet bubble destroyed vast amounts of shareholder wealth, yet the internet itself became indispensable.
Artificial intelligence may follow a similar pattern. Its commercial development could involve bankruptcies, consolidation, disappointing investments, and periods of public disillusionment without diminishing the technology’s long-term importance.
The more serious concern is that the AI industry has become so large, interconnected, and strategically important that its mistakes may extend far beyond Silicon Valley. Financial institutions, electrical utilities, local communities, governments, workers, students, and consumers are all becoming participants in an experiment whose ultimate consequences remain unknown.
And that raises a question that rarely receives a satisfactory answer: What would success actually look like?
For Nvidia, success means selling more chips. For Microsoft, Amazon, and Alphabet, it means expanding profitable computing services. For investors, it means financial returns. For Washington, it includes maintaining technological leadership over China. For workers, it means better jobs and higher living standards. For society, it might mean scientific discoveries, better healthcare, improved education, and greater prosperity.
These goals overlap, but they are not identical. Some may even conflict.
We do not need to choose between uncritical enthusiasm and apocalyptic pessimism. We need better information about costs, realistic expectations about benefits, sensible safeguards against identifiable dangers, and a willingness to distinguish genuine progress from promotional exaggeration.
Artificial intelligence is not necessarily falling toward disaster. It may be heading toward the sort of economic and institutional adjustment that every transformative technology eventually faces.
But the people holding the blanket should probably stop arguing about who owns it, how much it is worth, and whether the Chinese have a better one.
They might also consider the possibility that they are falling just as fast as the thing they are trying to catch.
And perhaps the most important question is not whether the seven giants will survive the landing but how big the splat will be.